How Buyer Leads, Showing Requests & Offers Work on Flat Fee Group Michigan
When unrepresented buyers or buyer's agents inquire about your Michigan MLS listing, leads are forwarded promptly so you never miss an opportunity to sell — including 0%-commission direct buyers.
- Unrepresented Buyer Leads Sent Straight to You: If a buyer without an agent buys your home on Bronze, Silver, or Gold, you pay $0 buyer-agent commission.
- Jump to Guide: I Have an Offer! Now What? (How to Handle & Counter Offers in Michigan) ↓
Buyer Inquiries and Leads
Platforms like Zillow, Realtor.com, Trulia, and Homes.com make money by selling buyer leads (also called inquiries) to real estate agents. These sites often sell the same ZIP code to multiple agents—sometimes 10–20 or more—so when a buyer submits a request, it gets routed to all of them instead of going straight to the home's listing agent. That's why a single online inquiry can trigger calls from several different agents.
Zillow calls its agent lead program Premier Agent, while Realtor.com uses Connections Plus.
With our flat fee MLS service, your property gets full exposure on the MLS and syndicates to these same major sites (Zillow, Realtor.com, etc.)—just like a traditional listing—but at a fraction of the cost. As a discount realtor option, we focus on getting your home maximum visibility without the high commissions.
The key advantage: Once listed on the MLS through us, buyer inquiries and leads from these platforms (and elsewhere) come directly to you or your chosen contact. You stay in control as the primary point of contact—no middleman agent splitting or reselling leads. Serious buyers who contact us will be directed straight to you, and we forward any relevant messages promptly.
Why our Flat Fee MLS Listing is best for sellers. If a buyer reaches out directly:
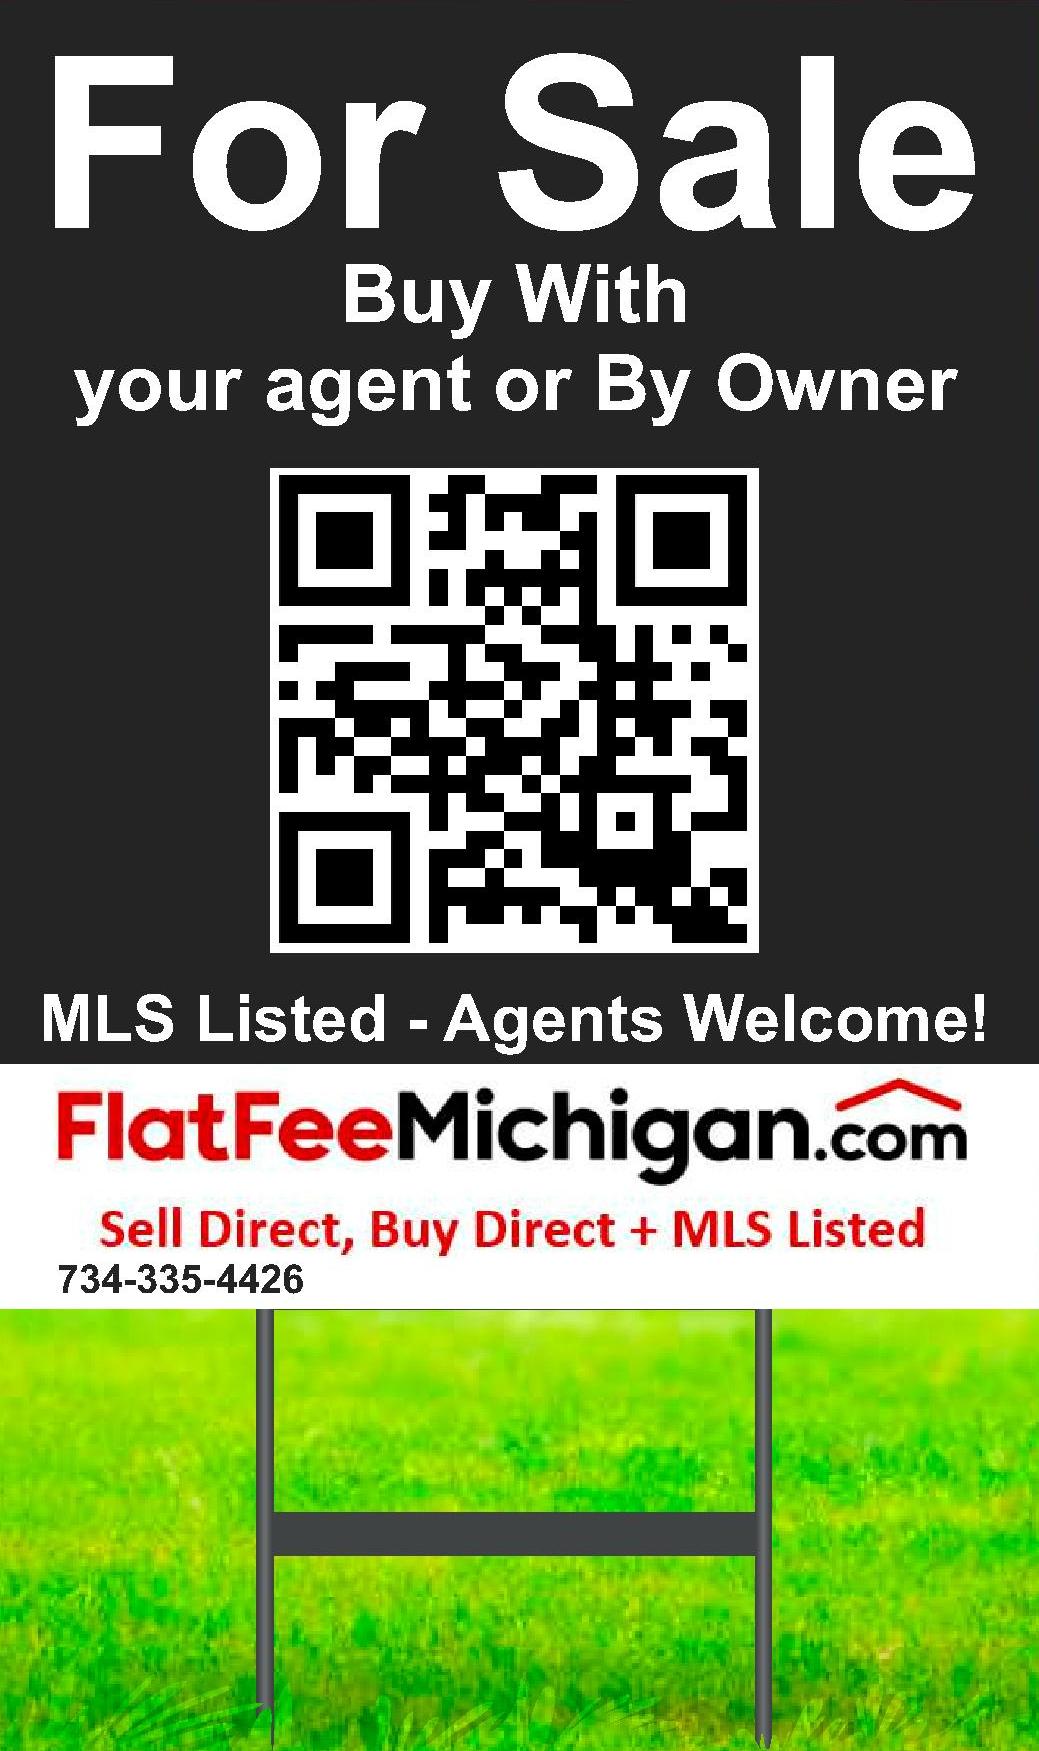
- Our yard sign has a qr code that directs fsbo buyers to our site, www.ShowMyListing.com. FSBO buyer's can search and contact you, the seller direct, thus avoiding buyer's agent fees.
- Visitors can contact you easily via our yard sign directing to www.ShowMyListing.com
This setup helps you capture buyer leads organically through your MLS listing, without paying ongoing fees for purchased leads. Many sellers choose our flat fee MLS model precisely because it puts more money in your pocket while still attracting motivated buyers—often at lower overall cost than traditional full-service agents.
If you have further questions, please contact the broker, Jeff Kermath / 734-649-4903 / jeff@flatfeemichigan.com.
I Have an Offer! Now What?
I have an offer, now what?
Most buyer’s expect to be countered so why let them down? Seriously, it is rare to make a counter offer and have the buyer just walk. Most buyers expect to be countered. Usually the offer / counter offer will go back and forth a few times until you can either come to terms or not come to terms.
It’s a poker game trying to determine how far up we can get the buyer but in the end it has to be a win-win for both parties so keep that in mind.
HOW TO MAKE THE COUNTER OFFER
- Typically, there is no counter offer form. You simply make changes to the offer. WHEN YOU MAKE ANY CHANGE TO AN OFFER IT BECOMES A COUNTER OFFER. REMEMBER THAT PLEASE!
- Draw a line through things you disagree with, make the change you desire (counter offer) then initial that change.
- Initial the bottom of each page of the offer form.
- Sign and date the last page of the offer.
- At the end of the offer or where there is space put a time period for your counter offer, typically 2 days. Something like, “This counter offer is good through….” This way your counter offer is not hanging out there and it protects you in case another offer comes in.
WHICH ITEMS ARE GENERALLY WORTH COUNTERING?
- Price: Again, draw a line through the price, put in the price you’re countering then initial the change.
- Occupancy: Many times the buyer will request occupancy at closing. If you want to remain in the home after closing for a short period put that period in there. If you remain in the home after closing for say 10 days you become a “Tenant” and will typically be obligated to pay rent. The rental amount is whatever the buyer’s mortgage payment is divided by 30 days to arrive at a daily rate, this is known as “1/30th PITI (principal, interest, taxes & insurance or tier total payment).
- Pre approval contingency: This is a big one as far as I am concerned. Most offers will contain a clause telling us when the buyer will be pre approved. Many times this pre approval is 30 days which is a long time to tie up your home in case something goes wrong! It should be 10-15 days. NOTE, MOST PRE APPROVALS ARE ABOUT AS GOOD AS TOILET PAPER SO BE AWARE! ALSO, MOST CONTRACTS DO NOT DEFINE PRE APPROVAL, THIS COULD MEAN ANYTHING, PRE APPROVED ON CREDIT, PRE APPROVED WHEN THE FINAL APPROVAL IS DONE WHICH IS NOT UNTIL THE APPRAISAL IS DONE JUST BEFORE CLOSING!
- So, be aware and hang tough on approvals. The last thing you needs as a seller is to wake up with a “Denial” a week before closing. You just lost 5 weeks of on market time when the buyer may not have had a strong (real) approval in the first place!
A WORD ON PRE APPROVALS / PRE QUALIFICATIONS: Most offers have a pre approval time period of 30 to 40 days. This means your home is “Off the market, pending” because there is a signed offer. Therefore, if something goes wrong with the buyer’s mortgage approval during that time frame you have essentially lost that “On market” time. It is wise to verify the “Mortgage approval” is actually a good one and not just toilet paper… I’ve seen too many bogus pre approvals…
Here is a clause I like to insert in the offer from (somewhere under additional conditions).
(I am not an attorney, have your attorney review this clause!)
“Buyer agrees to provide a full Credit Approval” within 15 days of acceptance of this offer. Credit approval means the lender has reviewed all income, bank statements, tax returns and other financial information and has approved the buyer.
Now, granted, this may be a little tough but it takes the risk out for sure!
This may eliminate approval issues as the file progresses. The only thing remaining for the lender to review would be the appraisal.
- The buyer will almost always hire an inspector. You should be contacted by the buyer’s agent to schedule an inspection on your home. The inspection generally lasts 3-4 hours. While it is your right to be there as owner it would be uncomfortable and few owners are there. However, it is not a bad idea to show up at the end and meet them outside to address any initial concerns if you wish.
- Appraisal is next. Assuming the inspection goes ok then the buyer’s mortgage company will hire the appraiser to appraise your home. This may take a week or so after the inspection.
- Title insurance needs to be ordered. Although you as seller may have title, you have to provide “Clear Title” for the purchaser. Title insurance confirms you are the owner and there are no other liens against the home. Title insurance is a set rate per thousand by Michigan Law. We can order it for you or you can choose a company you wish. Many times the buyer’s agent will order title for the buyer. This is a separate order for the buyer only. We can still choose any title company you wish and do not need to order it from the same company.
- How much can I expect to walk away with or what are my net proceeds? Here is a great calculator you can use for just that! See http://www.libertytitle.com/sellers-net-calculator/
- After the appraisal is done it should be clear sailing to closing.
- You’ll need to order a mortgage payoff if you owe on your home and a final water bill.
- The buyer’s mortgage company gets all of their information and costs to the title company. Generally, this is not done until a day or two prior to the closing date.
- The Closing: The title company acts like a big pot. Everyone dumps their stuff in the pot and the title company divides it up and produces a closing statement commonly referred to as a HUD-1. The closing statement is generally not available until a day or so prior to closing because the buyer’s mortgage company has to get their numbers to the title company first.
- You should be paid at closing. You can have the title company issue you a check or you can have it wired to your bank account.
I hope this helps explain the process.
Jeff Kermath
Flat Fee Group Michigan — Regional MLS & Seller Resource Directory
Kermath Realty LLC (Michigan Licensed Real Estate Broker #6502334057 • Verify License with MI LARA ↗ • BBB A+ Accredited ↗) is your direct, local Michigan MLS broker across all 83 Michigan counties — never a national referral middleman.
• Washtenaw County (Ann Arbor, Saline, Dexter, Chelsea)
• Greater Lansing MLS (Ingham, Eaton & Clinton Counties)
• West Michigan MichRIC (Grand Rapids, Holland, Kalamazoo)
• Northern Michigan NGLRMLS (Traverse City, Alpena, Gaylord)
• Petoskey, Harbor Springs, Emmet & Charlevoix MLS
• Upper Peninsula UPMLS (Marquette, Houghton, Escanaba, Sault)
• List Your Michigan Property Online Now
• Verified Michigan Seller Reviews & Commission Savings
• Houzeo & Referral Sites vs. Direct Michigan MLS Broker
• Investors, Flippers, Builders & Probate Estates Program
• Compare Us vs. 6% Traditional Realtors • How It Works
• Optional Full Service & Offer Negotiation • Full Service Do's & Don'ts
• ShowingTime & How To Do Showings • Virtual Showings
• What's My Net? Closing Costs, Title Insurance & Mortgages
• Home Inspections & What If Appraisal Comes In Low?
• What Separates Us & Why Not to Cancel/Relist Locally
• View Our Active Listings • MLS Rental Listings
• Michigan Home Buyer Rebates (Get 50% Commission Back)
-
- 734-649-4903
- 734-649-4903
- Lic# 6505334056 / Kermath Realty
- www.flatfeegroup.com/Michigan/
® Flat Fee Group, LLC. All Rights Reserved.
Flat Fee Group logo and service marks are owned by Flat Fee Group, LLC. Flat Fee Group, LLC is proud to be the largest organization of Flat Fee brokers in the United States and is registered for "Real estate multiple listing services; Real estate brokerage". Accept no alternative or referral companies when listing.
Acme | Ada | Addison | Alanson | Allegan County | Allen Park | Allendale | Ann Arbor | Ann Arbor MLS | AuSable | Bad Axe | Battle Creek | Beaverton | Bedford | Belleville | Detroit | Detroit Area MLS | Discount-Realtor | Flint | Genessee County | Grand Rapids | Grand Rapids MLS | Grand Traverse County | Holland | Ingham County | Kalamazoo | Kalamazoo County | Kent County | Lansing | Lansing MLS | Macomb County | Marquette | Midland | Midland MLS | MLS Listing | Monroe | Mount Pleasant | Muskegon | Oakland County | Owosso | Paul Bunyan MLS | Petoskey | Saline | Sturgis | SWMRIC MLS | Traverse City | Washtenaw County | Wayne County | Ypsilanti |
Best Flat Fee MLS Companies
Alabama | Alaska | Arizona | Arkansas | California | Colorado | Connecticut | Delaware | Florida | Georgia | Hawaii | Idaho | Illinois | Indiana | Iowa | Kansas | Kentucky | Louisiana | Maine | Maryland | Massachusetts | Michigan | Minnesota | Mississippi | Missouri | Montana | Nebraska | Nevada | New Hampshire | New Jersey | New Mexico | New York | North Carolina | North Dakota | Ohio | Oklahoma | Oregon | Pennsylvania | Rhode Island | South Carolina | South Dakota | Tennessee | Texas | Utah | Vermont | Virginia | Washington | West Virginia | Wisconsin | Wyoming |